Trusted By The Top 0.1% of Canadian Founders & Their Advisors For 20+ Years
For Canadian Business Owners & HNW Families With $1M+ In Annual Profit
We'll Uncover If You're Overpaying Tax, Group Insurance, Or Have Key-Man Risk In Just 15 Minutes
Video Explains: Why most advisors putting a $10M IFA proposal in front of you are General Practitioners — and what a specialist sees when they open the same document
Founders Who Already Closed The Gap
Business Partner / Co-Owner
Key Person Insurance | Business Continuity Protection
"When we set up key person insurance — life insurance and critical illness on both of us — the first thing it does is create a feeling of assurance and protection. Knowing that if something goes wrong, you're not left in the middle of nowhere with no way forward. It's not going to do the work for you, but it gives you time. It gives you a cushion, monetary and otherwise, so you can realign and figure out how to move the business forward if one of us is unable to carry on for a period of time."
Case details are specific to each client's corporate structure, health and carrier terms, and are shared with permission. Nothing here is a guarantee of a particular outcome.
Sibling Co-Owner & Business Operator
Second-Generation Shareholder | Planning for long-term business continuity
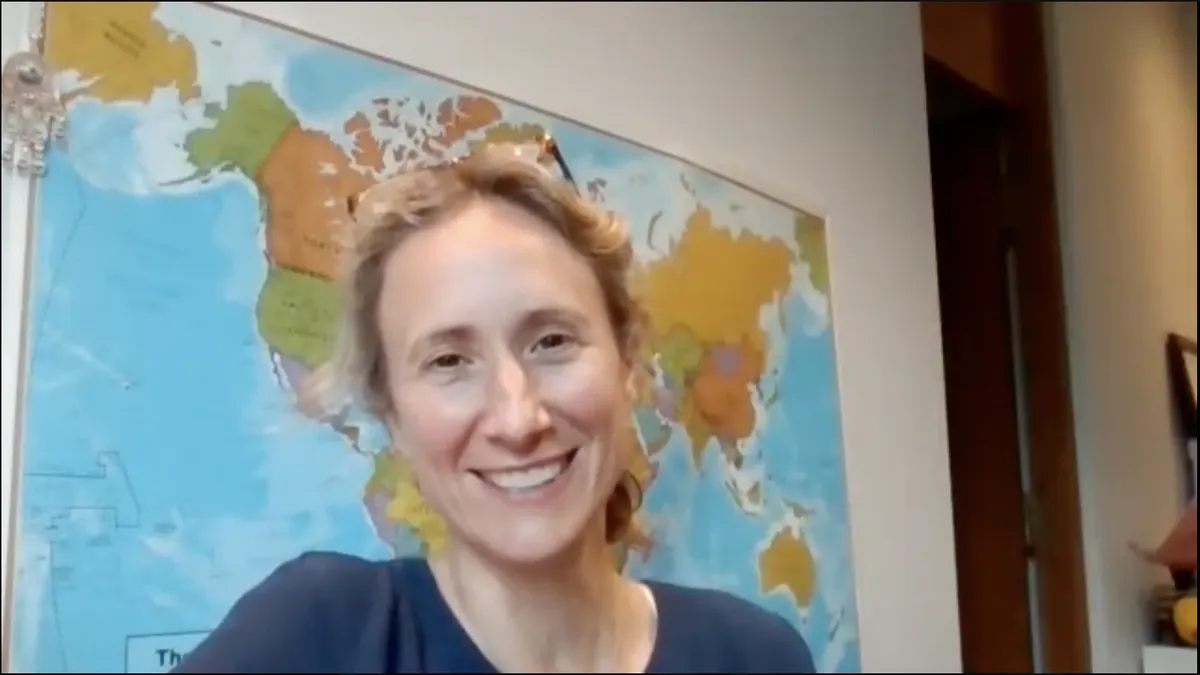
"Protecting my kids from a huge tax bill when I'm gone was always the priority — I watched my father set up a policy years ago to handle exactly this, so I know how much it matters to get ahead of it. On the business side, the bigger concern was the company itself. We didn't want a situation down the road where all the kids inherit shares and end up trying to run things together, whether they want to or not. This strategy gives the company the funds to buy back shares from the kids who don't want to stay involved, so ownership stays clean and the business isn't stuck in a tangle. It protects the next generation financially and keeps the company itself running the way it should."
Entrepreneur & Business Owner
International Manufacturer | Key Person Protection & Estate Planning
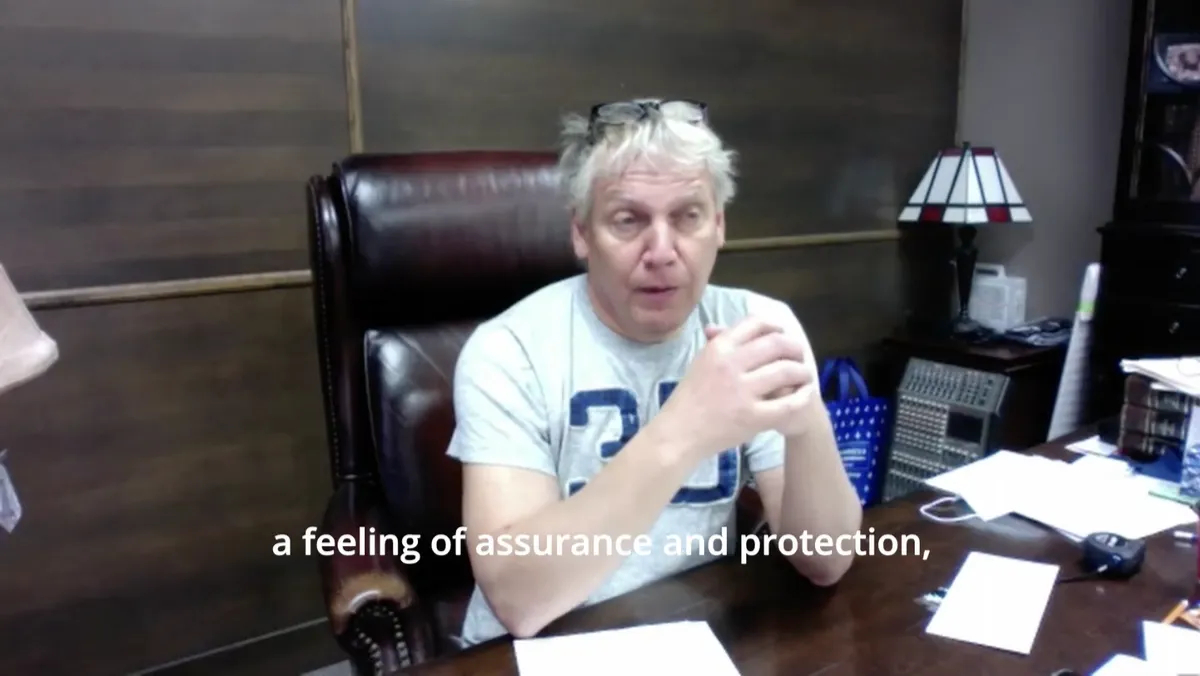
"I think all entrepreneurs believe they're invincible — that reality doesn't apply to them. It does, especially during those formative family years or once you hit that 50-to-65 risk bracket, right when the business is expanding fastest. Years ago, when my kids were young and I was the only income earner, my business wouldn't have survived without me. We put coverage in place to get my family through that gap. Today, with a more distributed management team, the business could carry on without me — but at the time, it couldn't, and the planning reflected that.
What Happens On The Call?
We look at what you already have
Existing policies, the proposal in front of you, your corporate
structure — the actual documents, not a hypothetical.
We show you where the structure leaks
Carrier choice, loan conditions, conversion mechanics, and the tax event when corporate wealth finally leaves the company.
We define your estate objective
What you intend to never spend, what your family should receive, and what your safest investments would have to earn after tax to match it.
You leave with a clear answer
Either your current proposal holds up — and we'll say so — or you'll see precisely what a specialist structure would change, in writing.
What happens on the 15-minute call?
I look at your specific situation — your company's profit, your current tax exposure, your retirement setup, your estate plan, your group insurance if you have it — and I tell you exactly where the gaps are. No slides. No presentation. Just me telling you what I see. If there's something I can help with, I'll tell you. If there's not, I'll tell you that too and you'll walk away with more clarity than you had before. Either way, the call is free.
Who is this for?
Business owners in Quebec who have built something real. Your company generates at least five hundred thousand dollars a year in profit. You're taking a salary of a hundred and fifty thousand or more. You've got fifty employees or more. And you've been doing this for ten, fifteen, twenty years. If that's you, you almost certainly have at least two or three of the five problems I talk about — and you probably don't know it yet.
How is this different from what my accountant already does?
Your accountant is great at what he does. He's maximized every deduction, structured everything he knows how to structure. But the strategies I'm talking about — the ones that can add three, five, ten million dollars to your estate value — your accountant isn't licensed to execute them. It's not his fault. It's just not his world. I'm not replacing your accountant. I'm picking up where he leaves off.
I already have a financial advisor. Do I need another one?
Maybe, maybe not. That's exactly what the fifteen minutes is for. Most of the business owners I work with have a financial advisor, an accountant, and an insurance broker — and none of those three are talking to each other. Nobody is looking at the full picture. That's the gap.
What does it cost to work with you?
The fifteen-minute strategy call is free. If we decide to work together after that, the cost depends entirely on your situation — the size of your company, the complexity of what needs to be done, and which of the five areas need attention. I'll give you the full picture on the call. No surprises, no hidden fees.
How quickly can I see results?
That depends on which areas need attention. Some things — like restructuring your group insurance — can start saving you money within sixty to ninety days. Others — like estate planning and corporate life insurance — take a bit longer to set up but the impact lasts decades. On the call, I'll tell you what's quick, what takes time, and what's most urgent.
This page is for information only and does not constitute tax, legal or investment advice. Insurance and financing structures are subject to underwriting, carrier approval and individual suitability. Discuss any strategy with your own accountant and legal counsel.